IN999 Withdrawal: link the destination before you need it
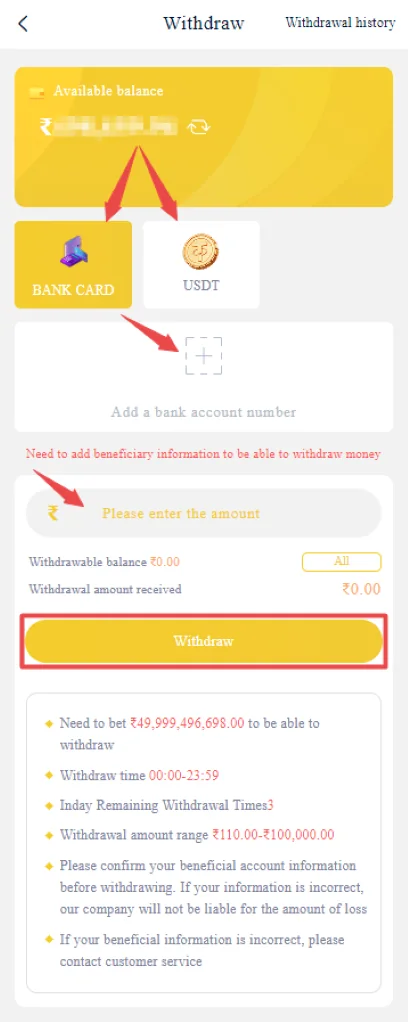
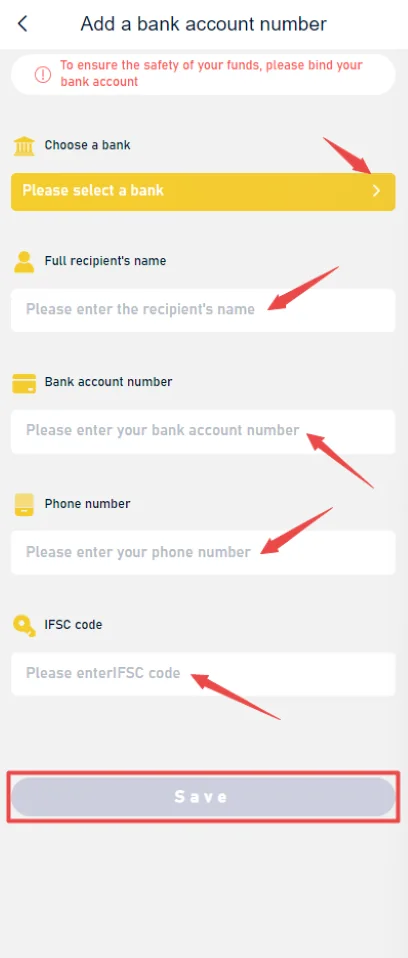
The withdrawal screen shown in the supplied assets separates bank-card and USDT-style destinations. A bank withdrawal can require bank name, recipient/account-holder name, account number, phone number and IFSC.
Add these details slowly and verify them before saving. A typo in the account number or IFSC can create a serious routing problem.
Bank account setup for withdrawal
Choose the bank carefully, enter the account holder name exactly as required, type the account number twice if the app offers confirmation, and verify the IFSC from a reliable banking source.
Do not copy bank details from an old message without checking them. If the bank account changes, update the linked destination through the supported account flow.
IN999 withdrawal pending
A pending withdrawal does not automatically mean it failed. Check the transaction status, submission time, amount and destination. Processing time can vary.
If the status does not change, use the service center with the withdrawal reference. Do not pay a stranger a ‘release fee’ to unlock a transaction.
Withdrawal safety
Never share a bank OTP, UPI PIN, debit-card PIN or app password. Customer support may need a transaction reference or masked account detail, but not the secret codes that authorize payments.
Bank account verification before the first IN999 withdrawal
Bank name, account holder name, account number and IFSC should describe the same account. Verify the IFSC from a reliable bank source and type the account number carefully.
If the app asks for a phone number in the bank-account form, use the number required by the active flow. Do not use a random number simply to pass validation.
Common reasons a withdrawal can remain pending
A withdrawal can be waiting for platform processing, account verification, bank processing or an internal review triggered by account/payment details. The status message is more useful than guessing based on elapsed time alone.
If a withdrawal is marked failed, check whether the amount returned to the in-app balance before submitting again. If it is still pending, avoid creating repeated requests unless the platform specifically instructs you to do so.
Wrong bank details: stop before resubmitting
If you notice an incorrect account number or IFSC after saving, do not keep testing withdrawals. Use the account/service path to correct the linked destination. Multiple failed attempts can make the history harder to follow.
Withdrawal evidence to preserve
- Withdrawal amount
- Submission time
- Transaction/reference number if shown
- Current status
- Masked bank/USDT destination
Those details allow a transaction to be traced without exposing the full account or secret credentials.
Release-fee scams
Be suspicious if someone asks you to send a separate personal payment to release a withdrawal, remove a freeze or increase a limit. Never share OTPs, PINs or passwords as part of a withdrawal “unlock.”
Withdrawal history and bank history should be checked together
The app can show a submitted withdrawal while the bank has not yet received it. Compare the in-app status with the bank statement. A completed in-app status without the expected bank credit is different from an in-app pending status.
Account-holder and IFSC mismatches
Use the real account holder name and current IFSC for the selected bank/branch. If a bank has merged or an IFSC changed, verify the current value instead of copying an old saved detail.
USDT-style withdrawal option
The supplied interface shows a USDT-style choice alongside bank card. Crypto destination details are unforgiving: verify the network and address shown in the active flow. Sending to the wrong network or address can be irreversible.
After a failed withdrawal
Check whether the amount returned to the in-app balance, note the failure reason if shown and fix the underlying destination or limit issue before submitting again. Repeating the same invalid details is unlikely to produce a different result.
Withdrawal amount limits and usable balance
A visible wallet balance is not always identical to the amount immediately available for withdrawal if the active rules include limits or unsettled activity. Check the withdrawal screen for the amount it accepts rather than assuming every displayed rupee is currently withdrawable.
Bank account number confirmation
When the form asks for the account number and then confirms it, type both carefully. Copy/paste can repeat the same typo twice. Reading the last four digits back against your banking app can catch simple errors.
IFSC and bank branch changes
IFSC codes can change after bank mergers or branch changes. Verify the current code from your bank rather than an old passbook image if you are unsure. A valid-looking but outdated code can delay or fail a transfer.
USDT network caution
If a crypto-style withdrawal is active, the address and network must match the destination wallet. Do not guess a network based only on the word USDT. A wrong network can lead to irreversible loss.
Withdrawal status timeline
Record when the request was submitted, when the status changed and when the destination received funds. That timeline makes it easier to distinguish platform processing time from bank/chain settlement time.
Do not cancel and resubmit repeatedly
If the platform supports cancellation, use it only when you understand the effect. Repeated cancellations and new requests can create multiple references and make support investigation harder.
Withdrawal destination review after a password change
If the password was changed because of suspicious activity, verify the linked bank/USDT destination before the next withdrawal. A secure password does not correct a destination that was altered earlier.
Bank credit can arrive after the app status changes
A completed status and bank credit may not appear at the exact same second. Keep the reference and compare timestamps. If the bank remains uncredited after a reasonable period, describe it as “completed in app, missing at destination” rather than simply “pending.”
Use one withdrawal case per reference
If several withdrawals exist, keep each reference separate. Mixing multiple amounts and dates in one message can lead to the wrong transaction being investigated.
IN999 withdrawal after changing a bank account
After adding or replacing a bank account, review the masked account number and name before the next withdrawal. If the old destination is still selected, stop before confirming. A small profile mistake can become a larger transaction problem once the withdrawal is submitted.
Withdrawal case closure
Close a withdrawal case only when the app status and destination record make sense together. Keep the reference until the bank or wallet credit is confirmed, especially when the app moves to a completed status before the receiving institution updates.
IN999 withdrawal status needs both the request record and receiving account record
A withdrawal can move through request, processing, completed or failed states before the receiving bank or wallet reflects the final credit. Preserve the withdrawal reference and compare both sides. A “completed” label is useful evidence, but the receiving account should also show the amount before the case is considered finished.
Withdrawal status matrix
Keep the reference and avoid submitting duplicates.
Check the receiving bank or wallet for the matching credit.
Confirm whether the balance returned before trying again.
Stop future requests and verify linked bank details immediately.
Frequently asked questions
How do I withdraw from IN999?
Open Withdrawal, select a linked bank or supported destination, enter an allowed amount and submit after checking the details.
Why does IN999 ask me to add a bank account?
A withdrawal needs a verified destination. Bank details normally include bank name, account holder name, account number, phone and IFSC.
Why is my withdrawal pending?
Processing, account verification, bank mismatch, limits or temporary service delay can leave a withdrawal pending.
Can I change the bank account later?
Account-management rules can vary. Verify every field before saving and use in-app support if a linked destination is wrong.
Should the bank account name match my identity?
Use accurate account-holder information. A mismatch can create verification or processing problems.
Can I withdraw to USDT?
The supplied screenshot shows bank-card and USDT-style options, but active availability can change.
What should I do if a withdrawal fails?
Check the linked destination, amount limits and status first, then contact in-app support with the transaction reference if one exists.